FINRA Series 6 Exam Prep That Turns a 60% Into a 90%
The distance between a 60 and a 90 on the FINRA Series 6 is rarely more reading. It is
accuracy inside one job function: 25 of the 50 scored questions ask you to give a customer
information, make a recommendation and keep the record straight. Candidates who stall in the
sixties recognise the products perfectly well but cannot match them to a person. Close that
one gap and the other three functions follow.
What actually separates a 60% from a 90% on the Series 6?
Put the two scores in whole questions and the problem stops being vague. The exam has 50
scored questions and a passing score of 70, so the pass mark is 35 correct answers. A 60%
paper is 30 right and 20 wrong. A 90% paper is 45 right and 5 wrong. The distance between
them is fifteen questions — not fifteen chapters, not a second textbook, fifteen
individual items that you are currently getting wrong for a reason you can name.
When candidates track their own mock papers by job function rather than by overall
percentage, the same shape appears almost every time. Regulatory recall is usually fine.
Account paperwork is usually fine. The losses cluster in the questions that put a customer
in front of you — an age, an income, a time horizon, a tax position, an existing
holding — and ask what you should do next. Those questions are not testing whether you
know what a variable annuity is. They are testing whether you can see why this particular
person should or should not be sold one.
There is a second, smaller gap, and it is purely mechanical. Ninety minutes for 50
questions gives you 108 seconds each. A candidate who spends four minutes arguing with
question 9 has borrowed that time from questions 46 to 50, which are answered in a rush and
lost. Scoring in the nineties almost always means finishing with time in hand, because the
easy items were taken quickly and the hard ones were flagged rather than wrestled with.
So the honest diagnosis has three parts: which function is leaking marks, whether the
losses are knowledge or reasoning, and whether the clock is making a bad section worse. The
rest of this guide works through each of them.
Which Series 6 job function is costing you the fifteen questions?
FINRA publishes the structure openly, and it is lopsided in a way that should change how
you spend your evenings. The
Series 6 exam page and the
Series 6 content outline divide the 50 scored questions into
four major job functions.
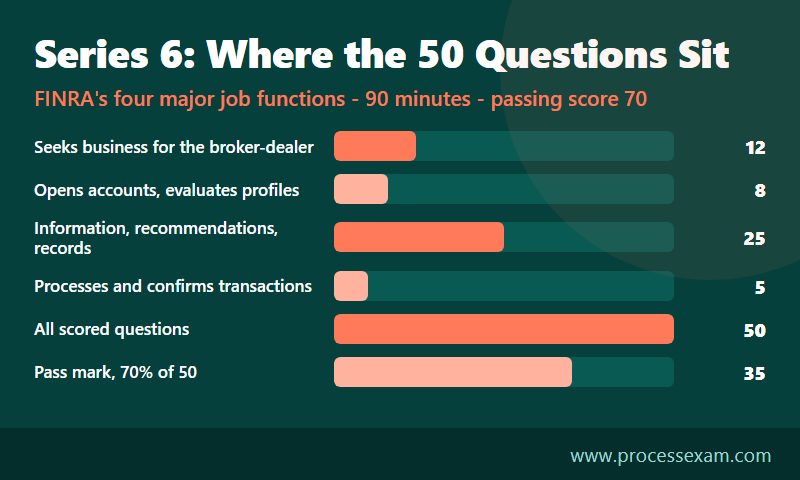
Function 1 — seeks business for the broker-dealer (12 questions)
Communications with the public sit here: the difference between retail communication,
correspondence and institutional communication, what has to be approved before it goes out,
what has to be filed, and how long records are kept. Telemarketing and do-not-call
obligations belong to this function too. It is a rules-heavy section, which is why most
candidates score reasonably on it and why the few marks they drop usually come from
confusing which category a given piece of material falls into.
Function 2 — opens accounts and evaluates financial profiles (8 questions)
The smallest function by count, covering account types and ownership, the customer
information a firm must obtain, investment objectives and risk tolerance, and anti-money
laundering obligations. Eight questions is not many, but they are cheap marks: the material
is finite and the question wording is usually direct.
Function 3 — information, recommendations, transfers and records (25 questions)
Half the exam. Product knowledge and suitability live here, along with transfers of assets
and the records a representative has to maintain. If your mock scores sit in the sixties,
this is where the missing fifteen questions almost certainly are, and it deserves half your
study time for exactly the reason it carries half the marks. Our
topic-by-topic breakdown of the Series 6 syllabus lists what sits
under each heading if you want to audit your own coverage before you start.
Function 4 — processes and confirms transactions (5 questions)
Five questions on obtaining and verifying purchase and sales instructions, processing
them and confirming them. It is the section candidates most often over-prepare, because it
is concrete and therefore comfortable. Learn it once, test it, and leave it alone.
Here are the figures you should have in front of you while you plan.
| What you are booking | Series 6 |
|---|---|
| Exam code | Series 6 |
| Full name | FINRA Investment Company and Variable Contracts Products Representative Exam |
| Awarding body | FINRA |
| Category | Representative-level |
| Scored questions | 50 |
| Time allowed | 90 minutes |
| Passing score | 70 |
| Fee | USD $100 |
| Co-requisite | Securities Industry Essentials (SIE) exam |
One correction worth making, because it circulates widely: FINRA's own exam page states
the number of items as 50 and does not publish a count of unscored pretest questions for the
Series 6. Plan your pacing against 50 in 90 minutes and treat any extra items you meet on the
day as a bonus rather than a surprise.
Do you need a sponsoring firm, and where does the SIE fit in?
This is the single most misunderstood part of the Series 6 route, and getting it wrong
costs people months. FINRA states plainly that candidates must be associated with and
sponsored by a FINRA member firm, or another applicable self-regulatory organisation member
firm, to be eligible to take representative-level qualification exams. The Series 6 is a
representative-level exam. Passing the SIE first does not remove that
requirement.
The two exams work as a pair. FINRA describes the SIE as a co-requisite to the Series 6:
you must pass both to obtain the Investment Company and Variable Contracts Products
registration, and FINRA's
exam restructuring FAQ confirms that the order in which you
pass them does not matter. What differs is who may sit them.
- The SIE is open. You must be 18 or older, and FINRA states you do not
need any association with a broker-dealer to take it. Students and career changers routinely
sit it before they have a job offer. - The Series 6 is gated. A member firm has to want you, and has to say so
formally by filing a Uniform Application for Securities Industry Registration (Form U4) on
your behalf through the Central Registration Depository. - Your SIE result keeps. FINRA states the SIE is valid for four years from
the date you pass it, which is what makes sitting it early a sensible move rather than a
gamble.
The practical sequence for most people, then, is: take the SIE while you are job hunting,
use the result as evidence of commitment during interviews, and let the firm that hires you
file the U4 and open your Series 6 enrolment window. Registration also involves fingerprinting
and a background review handled by the firm, so allow for that in your timeline rather than
assuming the exam date is the only date that matters.
If you are weighing the Series 6 against the Series 7, the gate is the same — both
are representative-level exams requiring sponsorship — but the scope is not. The Series
6 qualifies you for a defined product set. The Series 7 is the general securities
registration. Firms choose for you far more often than candidates choose for themselves.
Why do mutual fund and variable annuity questions stall so many candidates?
Because the exam does not ask you to define these products. It asks you to apply them, and
applying them means holding two things at once: how the product works mechanically, and what
that mechanism does to a specific customer's position.
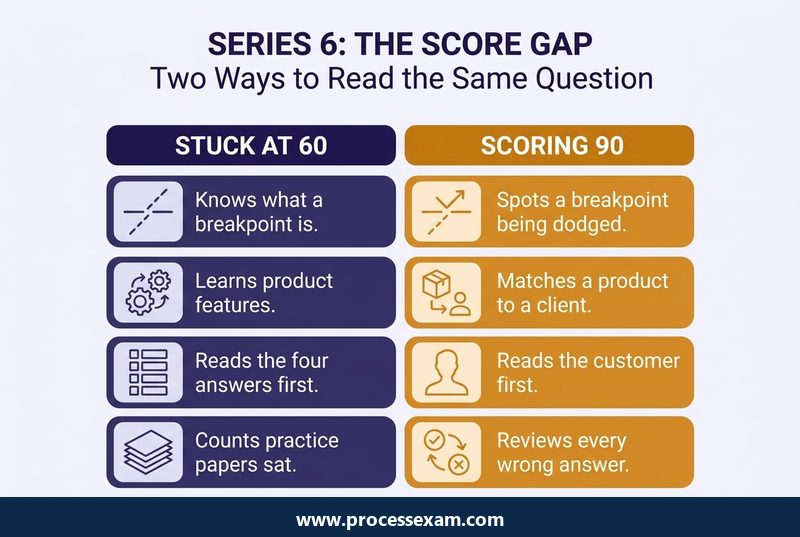
Sales charges are a suitability topic, not an arithmetic topic
You will be expected to know how a front-end sales charge, a contingent deferred sales
charge and an asset-based distribution fee each reach the investor, and which share class
carries which. But the question rarely stops there. It gives you an investor who intends to
add to the position, or who is about to cross a breakpoint, or who is being encouraged to
split a purchase across two fund families, and asks what the representative should do. The
knowledge is the easy half; recognising a breakpoint sale as a problem is the half that
separates scores.
Variable contracts reward knowing which phase you are in
Accumulation and annuitisation behave differently, and almost every hard variable annuity
question turns on which phase the customer is in and what that means for charges, access to
money, death benefit and tax treatment. Surrender periods, separate account investment risk
and the difference between a guarantee from the insurer and a market-driven value are all
places where a candidate who has only memorised a product sheet will guess.
Suitability is a comparison, not a rule
The strongest habit you can build for this function is to read the customer before you read
the options. Age, dependants, time horizon, liquidity needs, tax position, existing holdings
and stated objective are the facts the question is actually about; the four answer choices are
just products competing for that profile. Candidates who read the answers first talk
themselves into whichever one they recognise best.
Tax treatment is where careless marks go
Distributions, cost basis, exchanges within a fund family, and the treatment of withdrawals
from a variable contract all appear. None of it is conceptually hard, but it is detail that
decays quickly, so it belongs in your final fortnight rather than your first.
How should you use practice tests so the score actually moves?
Most candidates use practice questions as a thermometer. They sit a paper, note that they
got 68%, feel slightly worse, and go back to reading. Nothing changes because nothing was
diagnosed. Practice only raises a score when it is used as an instrument.
Four rules make the difference:
- Score by function, never overall. A single percentage tells you nothing
you can act on. Four percentages tell you exactly where the missing questions live. - Give every wrong answer a reason code. Did not know it, misread the
question, narrowed to two and chose wrong, or careless. Twenty wrong answers usually resolve
into two or three causes, and each cause has a different fix — more reading, slower
reading, sharper comparison, or better pacing. - Re-test the weak function alone. After a targeted study block, run a
short paper on that function only. If it has not moved, your study method is wrong, not your
study hours. - Run one full timed paper a week. Fifty questions in 90 minutes, no
pauses, no looking anything up. Stamina and the 108-second rhythm are trainable, and they are
worth several marks on their own.
When you want a full run under the clock rather than another chapter of reading, a timed
Series 6 practice exam is the quickest way to find out which of the
four functions is quietly costing you the marks.
A workable rhythm for the last month looks like this: week one, a baseline paper and a
brutal honest scoring by function; week two, the weakest function only, with a short
re-test at the end; week three, the second weakest, plus one full timed paper; week four,
mixed papers, the tax and recordkeeping detail that decays fastest, and a final full paper
no later than three days before your appointment. Do not sit a fresh mock the night before.
Nothing it tells you can be acted on, and a bad result will cost you sleep you need more.
What do the rules questions reward that memorising does not?
Regulatory items on the Series 6 are written to test application, and they do it with a
consistent trick: they describe a situation and ask which obligation is triggered, who has to
act, and when. A candidate who has memorised rule names answers the question the material
looks like. A candidate who has learned triggers answers the question actually asked.
Take communications with the public. Knowing the three categories is worth very little on
its own. Knowing that the category depends on who the material goes to and how many of them
there are — and that the category then determines approval, filing and retention —
is worth every mark in that part of the paper. The same applies across the function:
- Approval and review. Ask yourself who has to sign off before the material
leaves the firm, not merely whether sign-off exists. - Recordkeeping. The question is usually what must be kept and by whom,
rather than a period you can recite. - Anti-money laundering. Learn the behaviour patterns that raise a
question, not the statute. The exam gives you a customer doing something odd, not a
definition to complete. - Customer information. Know which facts a firm must obtain before an
account can be opened, and what happens when a customer refuses to provide one of them. - Prospectus delivery. Know the moment at which delivery is required, not
just that it is.
A simple drill converts recall into triggers. Take any rule in your notes and write one
sentence beginning “this applies when…” and a second beginning “the
person who must act is…”. If you cannot finish either sentence without looking
back at the page, you have memorised a label rather than learned a rule, and the exam will
find out.
What happens if you fail, and how soon can you sit again?
Nothing dramatic. A failed attempt is recorded, your firm is aware of it, and you pay the
USD $100 fee again for the retake. What you cannot do is walk back in the next morning.
Under FINRA's current waiting periods, a candidate who fails must wait 30 calendar days before
retaking the same exam, and a candidate who fails three or more times in succession within a
two-year period must wait 180 calendar days from the last attempt.
Those periods are under review. FINRA has filed a rule change that shortens both the
waiting period after an early failure and the longer period that follows repeated failures,
but it has said that the reduced periods are
not yet in effect for candidates and that the implementation date
will be announced in a future regulatory notice. Until that notice appears, plan against the
current periods and check FINRA's own page before you assume a shorter wait.
Use the gap properly. The score report breaks your performance down by job function, which
is the most useful diagnostic you will ever get for this exam, and it is free. Read it against
your own mock results. If the function that failed you is the same one your mocks were warning
you about, the problem was study priority. If it is a function your mocks said was strong, the
problem was pacing or nerves, and the fix is timed full papers rather than more content. Thirty
days is comfortably enough to close a fifteen-question gap when you know which fifteen.
Where does a Series 6 registration take you next?
The registration is deliberately bounded. Passing the Series 6 and the SIE qualifies you to
deal in investment company and variable contracts products: mutual funds, variable annuities
and variable life insurance, unit investment trusts, and municipal fund securities such as
529 college savings plans. It does not qualify you for individual stocks, corporate bonds,
options or direct participation programmes. That boundary is the point rather than a
limitation — it maps precisely onto how a great many retail financial roles actually
work.
It is the standard registration for bank-based investment representatives, for insurance
agents adding variable products to what they can offer, for mutual fund and annuity
wholesalers, and for client-facing roles at fund companies. Because the exam is 90 minutes
and USD $100 rather than a multi-day commitment, firms treat it as an early-career gate
rather than a milestone, which is exactly why treating it casually is expensive: it is short,
cheap and entirely capable of failing you.
Two things usually follow. Most firms pair the Series 6 with a state securities law
examination, administered by NASAA, before you may give advice for compensation in a given
state; your firm's registration team will tell you which one your role needs, because it
depends on the role and the state rather than on the Series 6 itself. And once you are
registered, FINRA's continuing education requirements apply for as long as the registration
does, so the studying does not stop at the pass mark — it simply changes shape.
If your ambitions run wider than investment company and variable contracts products, the
Series 7 is the usual next registration rather than a replacement, and it is a considerably
larger exam. Plenty of representatives never need it. Decide that question against the job you
want rather than against the exam you have just passed.
Frequently Asked Questions
How much does the FINRA Series 6 exam cost?
The Series 6 exam fee is USD $100. For that you get 50 scored questions in 90 minutes with a passing score of 70. The fee is payable again for a retake, and it does not include the SIE exam, which is a separate co-requisite with its own fee that your firm may or may not cover.
Do you need a sponsor to take the Series 6 exam?
Yes. FINRA requires candidates to be associated with and sponsored by a member firm or another applicable self-regulatory organisation member firm to sit representative-level exams, and the firm files a Form U4 on your behalf. Passing the SIE first does not remove the sponsorship requirement, although the SIE itself needs no firm.
What is the best way to study for the Series 6 exam?
Weight your time to match the paper. One job function carries 25 of the 50 questions, so product knowledge and suitability deserve about half your study hours. Score every mock by function rather than overall, log a reason for each wrong answer, and sit one full timed paper a week to build pacing.
What is the difference between the Series 6 and the Series 7?
Both are FINRA representative-level exams that need firm sponsorship, but they differ in scope. The Series 6 covers investment company and variable contracts products such as mutual funds, variable annuities and unit investment trusts. The Series 7 is the general securities registration and is a substantially longer exam.
What happens if you fail the FINRA Series 6 exam?
You receive a score report broken down by job function, pay the fee again and wait before retaking. FINRA's current waiting period is 30 calendar days after a failed attempt, extending to 180 calendar days after three or more failures within a two-year period. FINRA has filed a change shortening both, not yet in effect.
- FINRA Investment Company and Variable Contracts Products Representative Exam Questions |
- FINRA Investment Company and Variable Contracts Products Representative Exam Test Questions |
- Series 6 Question Bank |
- Representative-level |
- FINRA Investment Company and Variable Contracts Products Representative Exam Book |
- Investment Company and Variable Contracts Products Representative Exam Certification Cost |
- Investment Company and Variable Contracts Products Representative Exam Certification Requirements |
- FINRA Investment Company and Variable Contracts Products Representative Exam Sample Questions |
- Series 6 Exam Questions Download |
- Series 6 Test Questions |
- Investment Company and Variable Contracts Products Representative Exam PDF


