MLARM Certification: What It Does for a Financial Risk Career
MLARM will not hand you a new job title, but it gives a market risk officer, treasury analyst or finance controller a checkable way to show they understand the trading book and the balance sheet. PRMIA's exam is 60 multiple-choice questions in 2 hours, 60% is needed to pass, and the fee runs from $549 to $599 depending on membership tier.
PRMIA calls the credential a certificate, and most people search for it as the MLARM certification. Either way it covers three things that banks and treasuries return to after every crisis: market risk, liquidity risk and asset liability management. This guide looks at it from the career side. It asks who actually benefits, what the credential does and does not prove, what it costs, and how to fit the study around a job you already have. The exam facts come from PRMIA's MLARM certificate page and its candidate guidebook, revised March 2024, which were the current documents when this article was checked in October 2026.
What does the MLARM certification prove to a risk employer?
It proves that you have studied one defined body of knowledge to a set standard and passed a proctored exam on it. That is narrower than a broad risk designation and, for many roles, more useful. A hiring manager reading a CV that says MLARM knows which topics were examined: how market risk is governed, how trading-book exposures are measured, how stress tests go beyond Value at Risk, how a bank manages interest rate and liquidity risk on its balance sheet, and how funds transfer pricing allocates funding costs inside a bank.
PRMIA's guidebook lists what a holder has shown. Holders can describe the elements of market risk governance, apply the principles behind developments such as the Fundamental Review of the Trading Book, explain commodities risk management approaches, and discuss asset liability management after events such as the collapse of Silicon Valley Bank. They have also worked through case studies including Northern Rock and Lehman Brothers. Those are concrete, interview-ready topics, which is why the credential tends to help in conversations about judgement and context rather than in a keyword filter.
It does not prove years of experience, and PRMIA does not claim that it does. To enrol you need an account on PRMIA's website; paid membership is optional. There is also nothing to maintain afterwards: the guidebook states that no recertification requirements exist for any PRMIA certificate program, and holders are listed in the MLARM directory once they pass. For a busy professional that means the cost is paid once and the credential stays on the profile.
Here are the exam facts in one place.
| Exam detail | MLARM |
|---|---|
| Full name | PRMIA Market, Liquidity and Asset Liability Risk Management |
| Exam code | MLARM |
| Vendor | PRMIA |
| Number of questions | 60 |
| Duration | 120 minutes |
| Passing score | 60% |
| Price (USD) | Sustaining Member Price - $549; Contributing Member Price - $572; Non-member Price - $599 |
| Delivery | Pearson VUE test centre or online proctoring |
Which risk jobs gain the most from MLARM, and which gain the least?
PRMIA says the certificate is relevant to all risk-related roles in financial services, and names six groups in particular: market risk staff, treasury staff, financial controllers and people who manage the balance sheet, technology managers, and compliance and legal officers. It adds that a background in these techniques matters more and more for front-line staff dealing with clients and market counterparties. The graphic below turns that list into what each group typically gains.
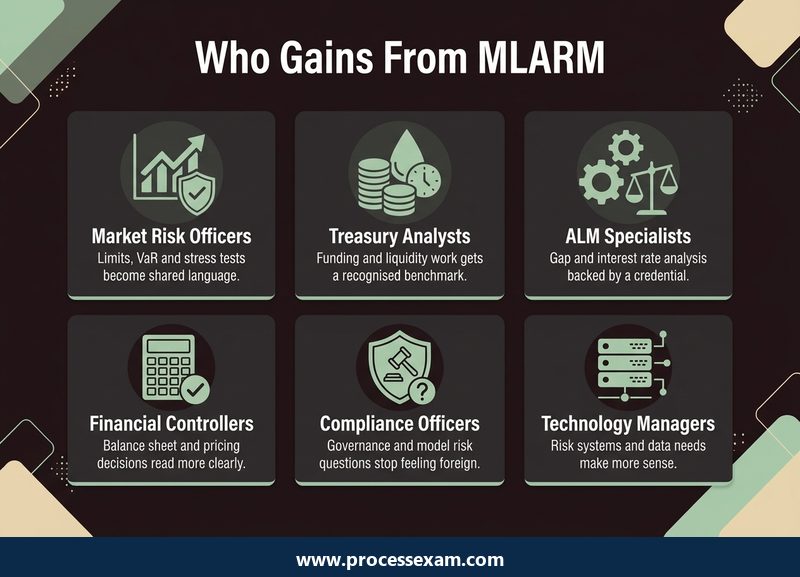
Market risk officers and analysts
This is the most direct fit. Limits, Value at Risk, stress scenarios and risk reporting are daily work, and the exam tests the reasoning behind them rather than the tools. A junior analyst who can explain why a limit framework exists, and not just how to update a spreadsheet, is easier to promote into a role that talks to committees.
Treasury and ALM specialists
Treasury teams work with funding, liquidity buffers, interest rate gaps and the asset liability committee. Four of the exam's areas sit squarely here: introduction to asset liability management, interest rate risk, liquidity risk and balance sheet management. For anyone planning a move from treasury operations towards ALM or liquidity risk, the credential turns a lateral wish into a documented step.
Finance controllers and balance sheet managers
Controllers see the numbers after the fact. MLARM explains the decisions upstream: how capital is managed, how funding is priced internally, what a contingency funding plan is for. That context helps when you sit in a pricing or planning meeting with treasury and risk.
Compliance, legal and technology staff
These groups rarely need to build a model, but they do need to understand model risk governance, limit policies and the data that risk systems depend on. The credential gives them the vocabulary to ask better questions, which is usually what these roles are valued for.
Where the benefit is smaller
If you already hold a broad risk designation and your work is credit or operational risk, MLARM adds less. It is a specialist certificate on market, liquidity and balance sheet risk, so it helps most where those topics are your job or the job you want. It is also not a substitute for hands-on experience, and a manager hiring a quantitative modeller will weigh coding and statistics skills above any certificate.
PRMIA's guidebook says current holders include staff from large banks, corporations, government agencies and other non-financial organisations, and names Bank of America, Barclays, Central Bank of Ireland, Deutsche Bank, KPMG and State Bank of India among the organisations represented. Treat that as evidence that the credential travels across employers, not as a promise about any particular hiring decision.
Do the syllabus areas match what a risk desk does all day?
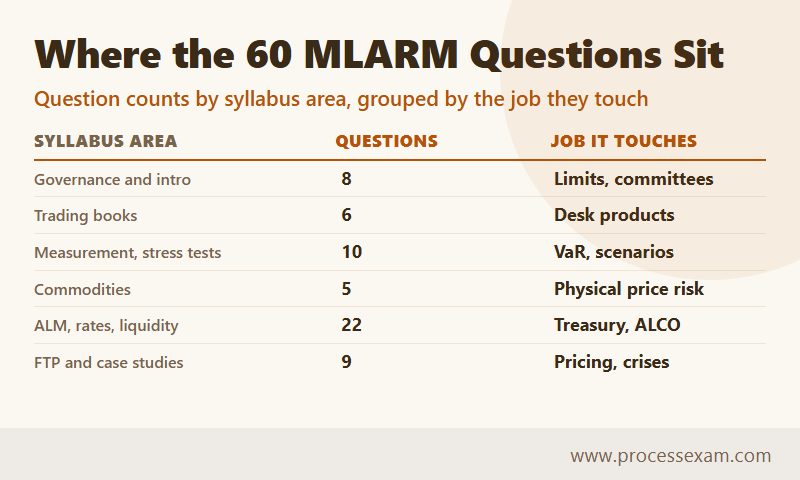
Mostly yes, and the match is the strongest argument for the credential. The syllabus has twelve domain areas plus case studies, and all of them map to something that happens in a bank every week. The table below links each area to the work it supports. The counts are the number of exam questions PRMIA assigns to each area, and they add up to the 60-question exam. The full topic list is on the MLARM syllabus page.
| Syllabus area (questions) | Where it shows up at work |
|---|---|
| Market Risk Introduction (2) | Explaining exposure types and recent events to non-specialists |
| Market Risk Governance and Management (6) | Risk appetite, limit policies, committees, model risk, audit |
| Market Risk in the Trading Books (6) | Fixed income, FX and rates, equity desks and their risks |
| Market Risk Measurement (5) | VaR models, advanced univariate and multivariate approaches, FRTB |
| Market Risk Stress Testing Beyond the VaR Threshold (5) | Scenario design, calibrating from history, systemic risk |
| Commodities Market Risk Management (5) | Physical-market risk, price risk management, commodity stress tests |
| Asset Liability Management and Recent Crises (3) | What the Great Financial Crisis and Silicon Valley Bank did to balance sheets |
| An Introduction to Asset Liability Management (5) | Gaps, banking book versus trading book, ALM roles |
| Interest Rate Risk (5) | Components, measurement and management of rate exposure |
| Liquidity Risk (5) | Fundamentals, measurement, recent developments |
| Balance Sheet Management (4) | The ALCO, capital management, contingency funding plans |
| Bank Funds Transfer Pricing (4) | FTP governance, methods, other challenges |
| MLARM Case Studies (5) | Silicon Valley Bank, Fannie Mae and Freddie Mac, LTCM, Northern Rock, AIG, Lehman Brothers, Washington Mutual |
Two things stand out. First, more than a third of the exam, 22 of the 60 questions, sits across asset liability management, interest rate risk, liquidity risk and balance sheet management, so a candidate from a pure trading background cannot lean on market risk alone. Second, the case studies are not decoration. Five questions draw on real failures, and they are the kind of material that comes up again in interviews: what went wrong at Northern Rock, why Lehman's funding failed, how a rate and liquidity mismatch hurt a modern bank.
Notice also what is missing. There is no coding, no long derivations and no essay writing. Every question is multiple choice with four options and one correct answer, and an online scientific calculator, the Texas Instruments TI-30XS, is built into the test system for the numerical items. The depth required is that of a practitioner who can reason about risk, not a researcher.
What does MLARM cost across the three membership tiers?
The price depends on how you stand with PRMIA. The fee is $549 at the Sustaining Member price, $572 at the Contributing Member price and $599 at the non-member price. The gap between the cheapest and dearest tier is $50, so membership alone is not a reason to join, but if you would join anyway for the chapter events and webinars, you save on the certificate. PRMIA's guidebook notes that paid membership is not required to enrol or to earn the certificate, and that Sustaining Members receive member pricing on the program and related fees.
What the fee buys is worth knowing before you ask an employer to pay. According to the guidebook, the program fee includes the authorisation to sit the required exam and access to the digital textbook, Risk Management Frameworks and Practices for Market Risk and Asset Liability Management, along with web-based resources. Candidates are told by email within two to three business days of payment how to reach the textbook and schedule the exam. In other words, there is no separate exam voucher and no required course.
Three money rules matter for planning. The program fee is not refundable or transferable. Changing an exam appointment through Pearson VUE costs nothing, but only if you do it at least one business day before the test date; otherwise the entire exam fee is forfeited. And a retake needs a separate retake fee, which PRMIA tells you how to buy after a fail. The guidebook does not state that fee, so check PRMIA's current fee page before you rely on a figure.
How to make the case to your employer
A short request works best. State the one-off cost, point out that it covers the textbook and the exam, show that the exam can be taken online or at a test centre, and name the topics your team has recently struggled with, such as liquidity stress testing or interest rate gap reporting. There is no renewal fee to defend next year, which is a real advantage over designations that charge annually.
What happens on exam day, and how hard is 36 out of 60?
You need 60% correct. PRMIA's guidebook turns that into a count: 36 of 60 questions. You have 2 hours, which is two minutes per question, so time is rarely the problem. Most of the effort goes into recall and judgement across a wide syllabus rather than into speed.
The exam is computer-based and in English only. You can sit it at a Pearson VUE test centre or take it online with a remote proctor. Plan to arrive at least 15 minutes before a test-centre appointment, or log in 30 minutes early for a remote one. Two forms of identification are required, and the first must be a current government-issued ID with a photograph and signature. Late arrivals may be turned away and still be charged. No paper may be brought in, but an erasable board is provided if you ask for one. The system lets you mark and review questions while time remains, so answer the easy ones first and return to the rest.
PRMIA publishes your result on your candidate profile within 15 business days of the sitting and emails you when it is ready. Candidates do not receive copies of the questions. If you do not pass, you can retake once 90 days have passed since the last attempt, after buying a retake. You must attempt the exam within 12 months of paying the program fee, and the guidebook says some candidates are ready with little study, which is why the enrolment window is generous.
As for difficulty, the guidebook gives no pass rate, so any figure you see online is a guess. The judgement call is personal. People who work in treasury will find the balance sheet areas familiar and the trading-book areas new. People from trading desks will find the reverse. Funds transfer pricing and the case studies are areas where even experienced staff often need fresh study, because day-to-day work seldom exposes you to all of it.
How can you fit MLARM study around a full-time risk job?
Treat it as a project with a start, a middle and a mock exam, and fit it into the hours you already have. The enrolment window is 12 months, so you are never forced to rush, but a plan with an end date prevents the study from sliding into next quarter. The example below assumes about six to eight hours a week. It is a suggestion, not a PRMIA rule.
| Stage | Focus | Output |
|---|---|---|
| Weeks 1-2 | Introduction, governance, trading-book context | One-page summary of the limit and committee structure |
| Weeks 3-4 | VaR, FRTB, stress testing, commodities | Worked examples for each VaR approach and a scenario list |
| Weeks 5-6 | Asset liability management, interest rate risk, liquidity risk | Gap table by hand, liquidity stress sketch |
| Week 7 | Balance sheet management, funds transfer pricing | Notes on the ALCO, capital and contingency funding |
| Week 8 | Case studies and timed practice | Error log of every missed question, sorted by area |
Start with the digital textbook that comes with enrolment, since it is the study material PRMIA provides. Read each area once for structure, then again with a pencil, turning headings into questions you could answer aloud. For the quantitative items, practise on paper with a similar scientific calculator to the one built into the exam, since fumbling an unfamiliar calculator costs minutes under pressure.
Link every topic to something at your own bank. If your team reports VaR, look at the actual report. If treasury runs an interest rate gap table, ask for a copy. The material sticks when it is attached to something you have seen at work, and the questions then feel like variations on familiar situations.
Practice under exam conditions is what separates a confident sitting from a nervous one. When you reach week eight, use the MLARM practice exam from ProcessExam to run a full 60-question, 120-minute attempt, then sort every miss by syllabus area and go back to the weakest two before booking your slot. Repeat a short timed set a few days before the exam rather than cramming new topics.
Common planning slips
- Leaving funds transfer pricing and the case studies to the last weekend, when they are worth 9 of the 60 questions together.
- Studying only the area you already work in and hoping the rest is easy.
- Booking the exam before you have run one full timed attempt.
- Forgetting that the enrolment window runs from the date you pay, not from the date you start reading.
Is MLARM worth it for your next career step, or is another PRMIA path better?
It is worth it when your role or your target role sits in market risk, treasury, ALM, liquidity or balance sheet management, and when you want a focused credential rather than a multi-year designation. The cost is a single fee between $549 and $599, with no annual dues and no recertification. The time is a couple of months of evenings. Few risk qualifications are this contained.
On salary, be careful. Many articles quote ranges for MLARM holders, but PRMIA's guidebook gives no earnings data for the certificate, and no salary survey isolates it from the job title and location behind a pay figure. This guide does not quote one. A more reliable approach is to look at advertised roles in your own market, note which ask for a risk certificate, and compare that with the fee. If your employer funds the exam, the return is simply the time spent.
Consider alternatives when the fit is weaker. PRMIA's guidebook lists several programs besides this one, including the Associate PRM, ORM and CCRM, and it describes the Professional Risk Manager designation as the broader qualification on which the certificate topics are based. A candidate whose work is mainly credit or counterparty exposure may be better served by the credit-focused certificate, and someone seeking a comprehensive designation may prefer the PRM route. MLARM is the better choice when your day involves rates, funding, liquidity and the trading book.
One question to ask before paying: could you explain, to a colleague, how a bank's funding position changed in a crisis such as Silicon Valley Bank, and how it should have been measured and managed? If the answer is yes, you need the certificate for proof. If the answer is no, you need it for the knowledge, which is an even better reason. Either way, the credential gives your CV a specific, checkable claim, and the preparation leaves you more useful in the meetings that matter.
Frequently Asked Questions
What is the MLARM certification?
MLARM is PRMIA's Market, Liquidity and Asset Liability Risk Management certificate. It tests market risk governance, measurement and stress testing, interest rate and liquidity risk, balance sheet management and funds transfer pricing, plus case studies such as Lehman Brothers and Silicon Valley Bank, in one 60-question multiple-choice exam.
Is the MLARM certification worth it?
It is worth it if your work or target role involves market risk, treasury, liquidity or asset liability management. The fee is a one-off $549 to $599 by membership tier, with no recertification. It matters less if your work is mainly credit or operational risk, where other PRMIA programs fit better.
How many questions are on the MLARM exam and what score passes?
The MLARM exam has 60 multiple-choice questions and a 120-minute limit. A score of 60% is needed to pass, which PRMIA's guidebook states as 36 of 60 questions correct. Each question has four options with one correct answer, and PRMIA releases results within 15 business days.
How much does the MLARM exam cost?
The price depends on membership tier: $549 at the Sustaining Member price, $572 at the Contributing Member price and $599 for non-members. PRMIA's guidebook says the program fee includes the exam authorisation and a digital textbook. The fee is not refundable, and a retake needs a separate purchase.
Does the MLARM certificate expire?
No. PRMIA's guidebook states there are no maintenance or recertification requirements for the MLARM certificate. Holders are expected to keep to PRMIA's Standards of Best Practice, Conduct and Ethics, and they appear in the MLARM directory after passing. You do not pay annual renewal fees to keep the credential.
- Risk Management |
- PRMIA Market Liquidity and Asset Liability Risk Management Test Questions |
- MLARM Question Bank |
- MLARM Body of Knowledge (BOK) |
- Market Liquidity and Asset Liability Risk Management Simulator |
- Market Liquidity and Asset Liability Risk Management Mock Exam |
- PRMIA Market Liquidity and Asset Liability Risk Management Book |
- PRMIA MLARM BOK PDF |
- Market Liquidity and Asset Liability Risk Management Certification Cost |
- Market Liquidity and Asset Liability Risk Management Certification Requirements |
- PRMIA Market Liquidity and Asset Liability Risk Management Sample Questions |
- MLARM Exam Questions Download |
- MLARM Test Questions |
- Market Liquidity and Asset Liability Risk Management PDF


